#saas
197 articles · page 6 of 17

15. Blackstone, KKR, and Silver Lake Aren't Competing With Each Other. They're All Buying the Same Asset - Data-Controlled Distribution - From Founders Who Don't Know What They Actually Have.
Private equity is buying the data pipelines and workflow systems that validate and distribute AI outputs—distribution, not models.
14. AI Didn't Kill SaaS. Founders Who Never Owned Their Distribution Did.
Own email lists, communities, integrations and growth loops to survive AI disruptions, cut CAC, and improve retention.

13. Between $5 Trillion and $8 Trillion in Capital Expenditures Will Flow Into AI Infrastructure by 2030. The Winners Aren't the Companies Building the Models. They're the Ones Who Own the Pipes. PwC
AI infrastructure will draw $5–8 trillion by 2030—data centers, power and cooling owners will capture the biggest gains.

12. PE Has $2 Trillion in Dry Powder and a "Deploy or Return" Mandate. Every Dollar Chasing the Same Thesis: Own the Data. Own the Distribution. Everything Else Is Leverage. FinancialContent
PE firms with $2T dry powder favor SaaS and AI companies that own proprietary data and distribution for faster, defensible growth.
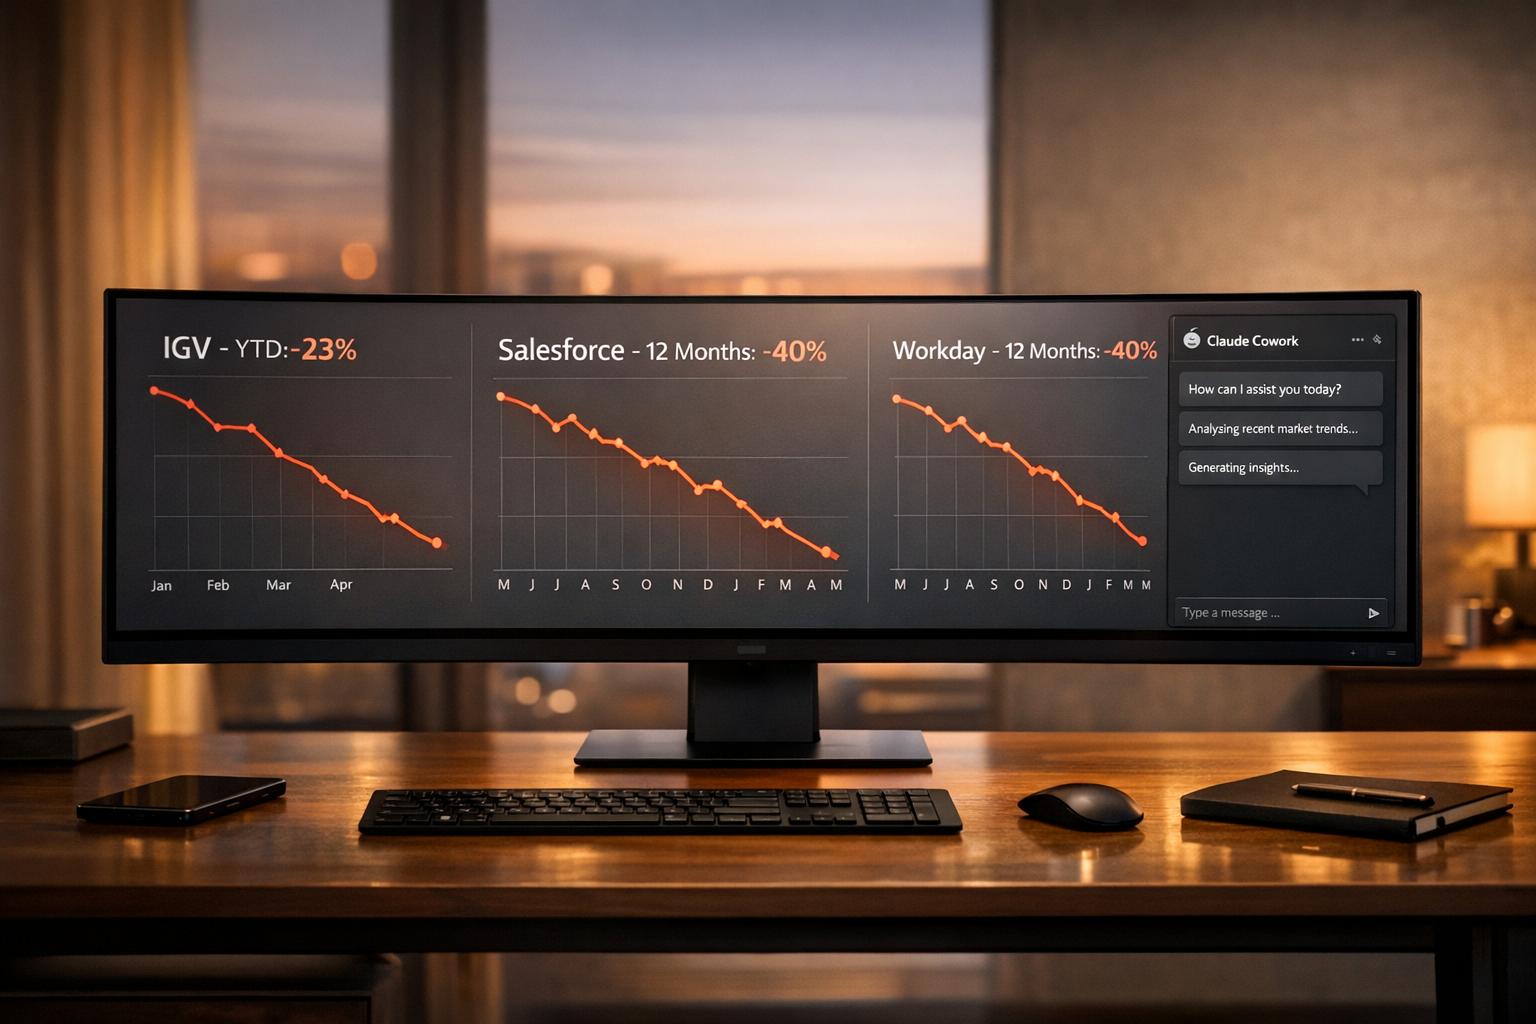
11. The iShares Software ETF Is Down 23% Year-to-Date. Anthropic Launched One Product. Salesforce and Workday Are Each Down 40% in 12 Months. These Are Not Random Events. Ai2
AI agents and Anthropic's Claude Cowork sparked a massive software reprice: IGV -23%, Salesforce & Workday -40%, per-seat SaaS under threat.

10. Same ARR. Same Revenue. Different Buyer Underwriting. A 1–3x Multiple Premium Is a $7.5M to $15M Swing on the Same Business. Most Founders Don't Even Know This Metric Exists. Livmo
Revenue quality — not ARR — drives SaaS exit value; NRR, multi-year contracts, and customer concentration can swing multiples by millions.
8. $4.9 Trillion in M&A in 2025. A Record. 25% of Every Deal Over $5 Billion Had an AI Theme. This Is Not a Cycle. This Is a Structural Shift in Who Controls Valuable Assets. CNBC
2025 hit a $4.9T M&A record as AI powered 25% of megadeals, shifting acquisitions to data, chips, energy and core capabilities.
7. The Private Credit Market Has $600 Billion Bet on Software Companies That AI Is Now Replacing. This Is the Quiet Crisis Nobody Is Tracking.
AI is replacing legacy SaaS, risking $600B in private-credit loans and spiking defaults, maturities, and BDC strain.

6. Steve Huffman Looked at Google and OpenAI and Said "We're Not Giving Our Data Away for Free Anymore." Every SaaS Founder Should Read That Sentence Again. TechCrunch
How SaaS founders can stop free data leakage: audit datasets, add paid APIs, enforce licenses, and turn user content into revenue.

5. Your SaaS Customers Are Generating Data Worth More Than Your ARR. You Don't Own Any of It.
Customer data can be more valuable than ARR but is limited by GDPR/CCPA; adopt privacy-first analytics, synthetic data, and clear policies.
4. The Reason Silver Lake Paid $56.5 Billion for a Gaming Company Has Nothing to Do With Games.
The EA buyout was driven by its Frostbite tech, AI systems, recurring revenue and 700M-user data—not the games themselves.

3. From 2015 to 2025, PE Acquired 1,900 Software Companies for $440 Billion. AI Is Now Dismantling the Thesis Behind Every Single One. Nobody on Wall Street Wants to Say It First. SaaStr
AI is eroding SaaS revenues, margins and valuations, forcing private equity to reassess $440B in deals and pivot to AI infrastructure.